How to Automate Invoice Processing Securely
A supplier invoice can arrive as a PDF, a photograph, an emailed attachment or an electronic file. That variety is exactly why accounts teams lose time rekeying data, chasing approvals and correcting avoidable errors. Learning how to automate invoice processing securely is not simply about processing invoices faster. It is about protecting payments, supplier information and the controls that keep cash flowing in the right direction.
For a small business, the right approach reduces manual administration without handing decision-making to a system you cannot see or trust. Automation should make the process clearer, not create a new black box.
Start with the process, not the software
Invoice automation works best when it follows a defined accounts payable process. Before choosing a platform or connecting it to your accounting package, map what happens from the moment an invoice arrives to the moment it is paid.
Look at where invoices are received, who checks them, how purchase orders are matched, who approves different spending levels and where the final payment instruction is created. Many businesses find the real problem is not data entry alone. It is invoices sitting in individual inboxes, unclear approval limits or suppliers changing bank details without a consistent verification process.
Set a simple rule: invoices should enter through a controlled route, such as a dedicated accounts email address, supplier portal or secure document capture tool. Avoid relying on staff to forward invoices from personal mailboxes. It is harder to track, easier to miss a document and creates unnecessary exposure if an account is compromised.
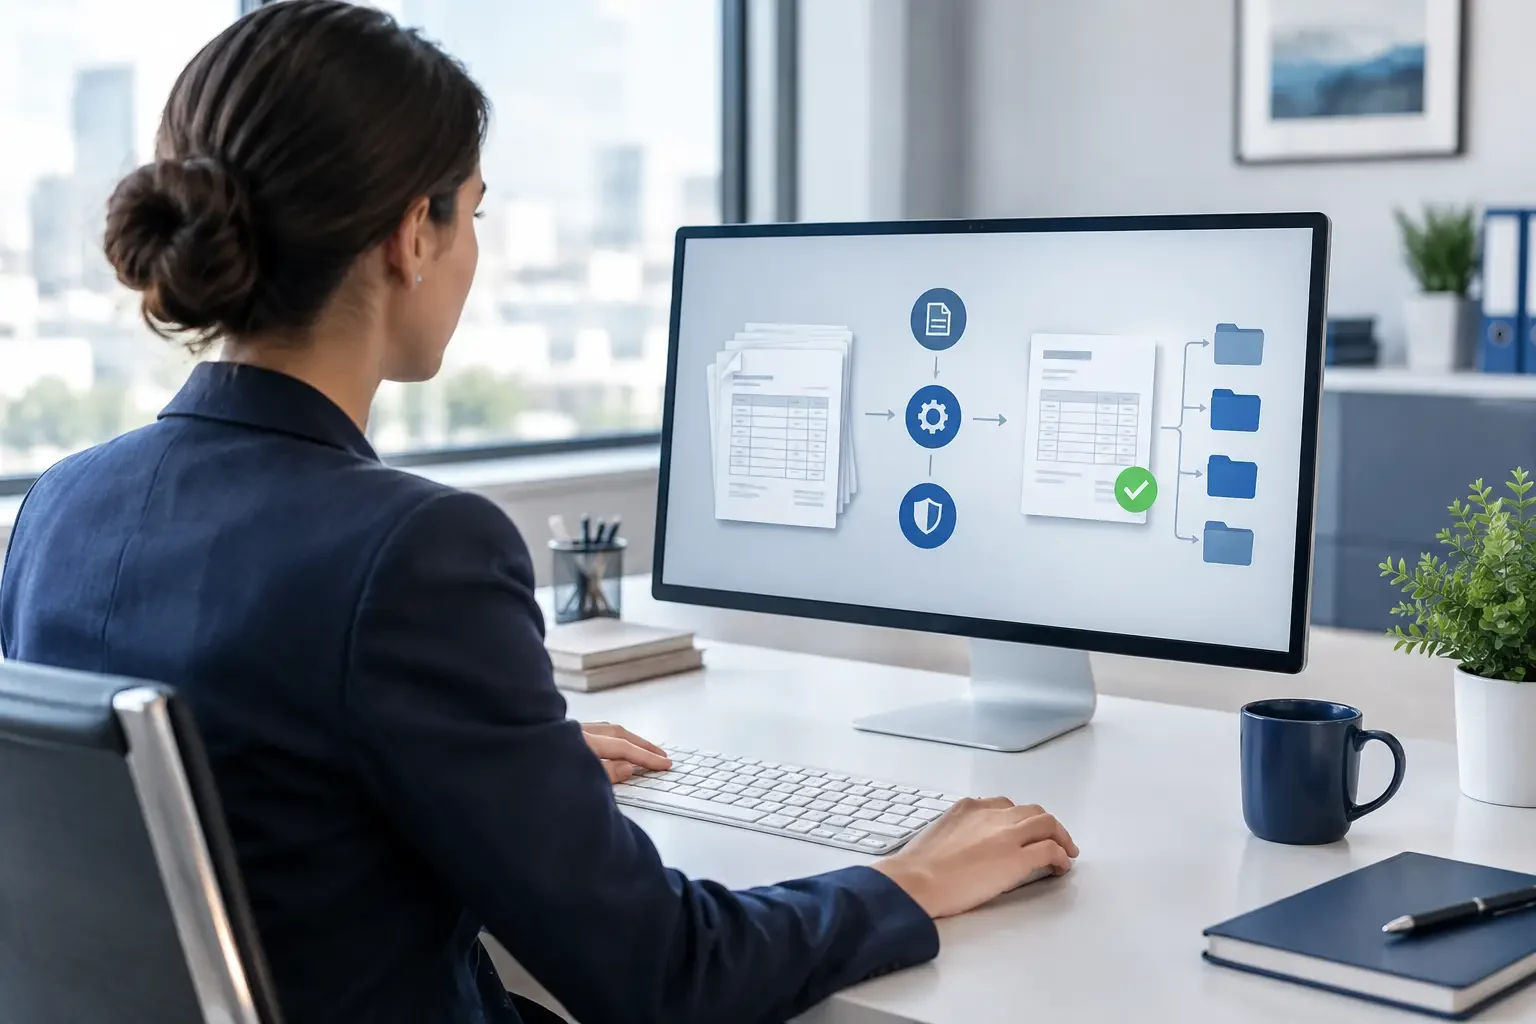
Automation can then capture key fields such as the supplier name, invoice number, date, VAT amount, line items and total. The system should pass that information into a review and approval workflow, rather than automatically treating every extracted value as correct.
How to automate invoice processing securely with layered checks
The most effective controls are layered. No single setting, staff member or software feature should be the only thing standing between a convincing fraudulent invoice and a payment leaving the bank account.
A secure workflow usually combines automated extraction, validation rules, approval routing and payment separation. The system handles repeatable work, while people retain responsibility for exceptions and payment decisions.
Match invoices to real orders and receipts
Where your business uses purchase orders, apply two-way or three-way matching. A two-way match compares the invoice to the purchase order. A three-way match also checks that goods or services were received.
This is particularly useful for businesses buying parts, equipment or regular services. If an invoice amount exceeds the order, contains a duplicate invoice number or comes from an unknown supplier, it should be held for review. The point is not to stop every unusual invoice. It is to make unusual items visible before payment.
Not every organisation can use purchase orders for every cost. Professional services, utilities and recurring subscriptions may need a different route. In those cases, set expected cost ranges, approved supplier lists and budget owner checks. Security needs to reflect how the business actually buys, or staff will work around the process when they are under pressure.
Build approval rules around risk and value
A sensible approval workflow reflects your organisation’s size and spending patterns. Low-value, routine invoices from established suppliers may need one budget-holder approval. Higher-value invoices, new suppliers or urgent payment requests should require additional scrutiny.
Avoid giving one person the ability to add a supplier, approve an invoice and release a payment. This separation of duties is one of the most practical defences against both error and fraud. In a smaller team, complete separation may not be realistic, but a director or independent colleague can review the payment run before it is submitted.
Approval notifications should be useful, not noisy. Include the invoice image, purchase order details, coding and any exceptions so the approver can make a proper decision. An approval button without context encourages rubber-stamping.
Treat bank detail changes as high risk
Invoice fraud often relies on a simple request to change supplier bank details. An attacker may impersonate a known supplier, use a lookalike email address and create a convincing explanation about a new bank account.
Never rely solely on an email, invoice footer or automated workflow to validate changed payment details. Require an independent call-back to a known telephone number already held on your records, not a number included in the request. Record who completed the check and when.
Your automation platform can help by flagging changes, restricting who can edit supplier records and keeping an audit trail. It cannot replace a human verification step. This is one of the clearest examples of where secure automation means knowing when not to automate the final decision.
Protect the systems around the workflow
Invoice automation touches valuable business data. Invoices may contain addresses, bank details, contracts, pricing and information about customers or projects. The accounting system may also sit close to payroll, banking and tax records.
Use a platform that supports multi-factor authentication, role-based access and activity logs. Each person should have access only to the functions they need. An accounts assistant may upload and code invoices, for example, while only authorised finance staff can amend supplier bank details or export payment files.
Use individual accounts rather than shared logins. Shared credentials make it difficult to investigate errors or suspicious activity, and they are often left active long after a member of staff has moved on. Review access when roles change and remove it promptly when someone leaves.
The email account used to receive invoices also needs protection. Multi-factor authentication, strong password management and anti-phishing controls matter here because a compromised mailbox can become a route into the entire finance process. Keep staff aware of common warning signs, including unexpected urgency, altered bank details and email addresses that are almost, but not quite, correct.
Keep data where you can manage it
Cloud invoice tools can be a good fit for small businesses because they reduce reliance on paper files and allow authorised staff to review invoices from different locations. However, convenience should not mean accepting vague answers about where data is stored, who can access it or how long it is retained.
Check the provider’s security arrangements, data protection commitments, backup approach and ability to export your records if you change systems. Consider whether it connects directly with your accounting software, banking platform and document storage, and limit integrations to those that have a genuine purpose.
A poorly managed integration can create a weak point. If an application no longer serves the business, remove its access rather than leaving it connected indefinitely.
Test before you trust the workflow
Do not switch on automatic processing for every invoice on day one. Begin with a defined group, such as routine invoices from a handful of established suppliers. Check how accurately the system reads documents, applies VAT treatment, identifies duplicates and routes approvals.
Run the automated workflow alongside your existing checks for a short period. Measure exceptions, approval delays, duplicate invoices caught and time saved by the accounts team. These figures show whether the process is improving, rather than simply moving work from one place to another.
Review the rules after the first month and then at regular intervals. Suppliers change, staff roles move, purchase patterns shift and fraud tactics evolve. A workflow that was appropriate a year ago may now have approval limits that are too broad or users with access they no longer need.
Keep a clear procedure for failures as well. If the invoice platform is unavailable, staff should know how to record invoices, seek approvals and prevent duplicate payments during recovery. This is where backups, documented processes and a tested business continuity plan become practical safeguards rather than paperwork.
Make automation accountable
The aim is not to remove people from invoice processing. It is to remove repetitive work while making the important decisions more visible. A good system gives finance staff a clear queue, managers a straightforward approval route and directors confidence that payments can be traced back to a valid business need.
For many Sussex businesses, the right setup will depend on the accounting package already in use, the volume of invoices, the level of purchasing control and whether staff work across several sites. A garage ordering parts every day will need different rules from a charity managing grant-funded spending, but both benefit from clear approvals and protected supplier records.
If your current process relies on emailed PDFs, shared passwords and manual payment checks, begin with a review of the risks before adding more technology. My Tech Team can help assess the systems, permissions and security controls around your finance workflow, so automation supports the way your business works and gives your team more time for the work that needs their judgement.